Editorial Deep Dive
QuantConnect Review 2026: From First Backtest to Live Trading
Read the full QuantConnect teardown- Length4,700 words
- Read time21 min
- RefreshedEvery 6 to 12 months
The most capable retail backtesting stack there is, and the seat price on the pricing page is not what you will pay.
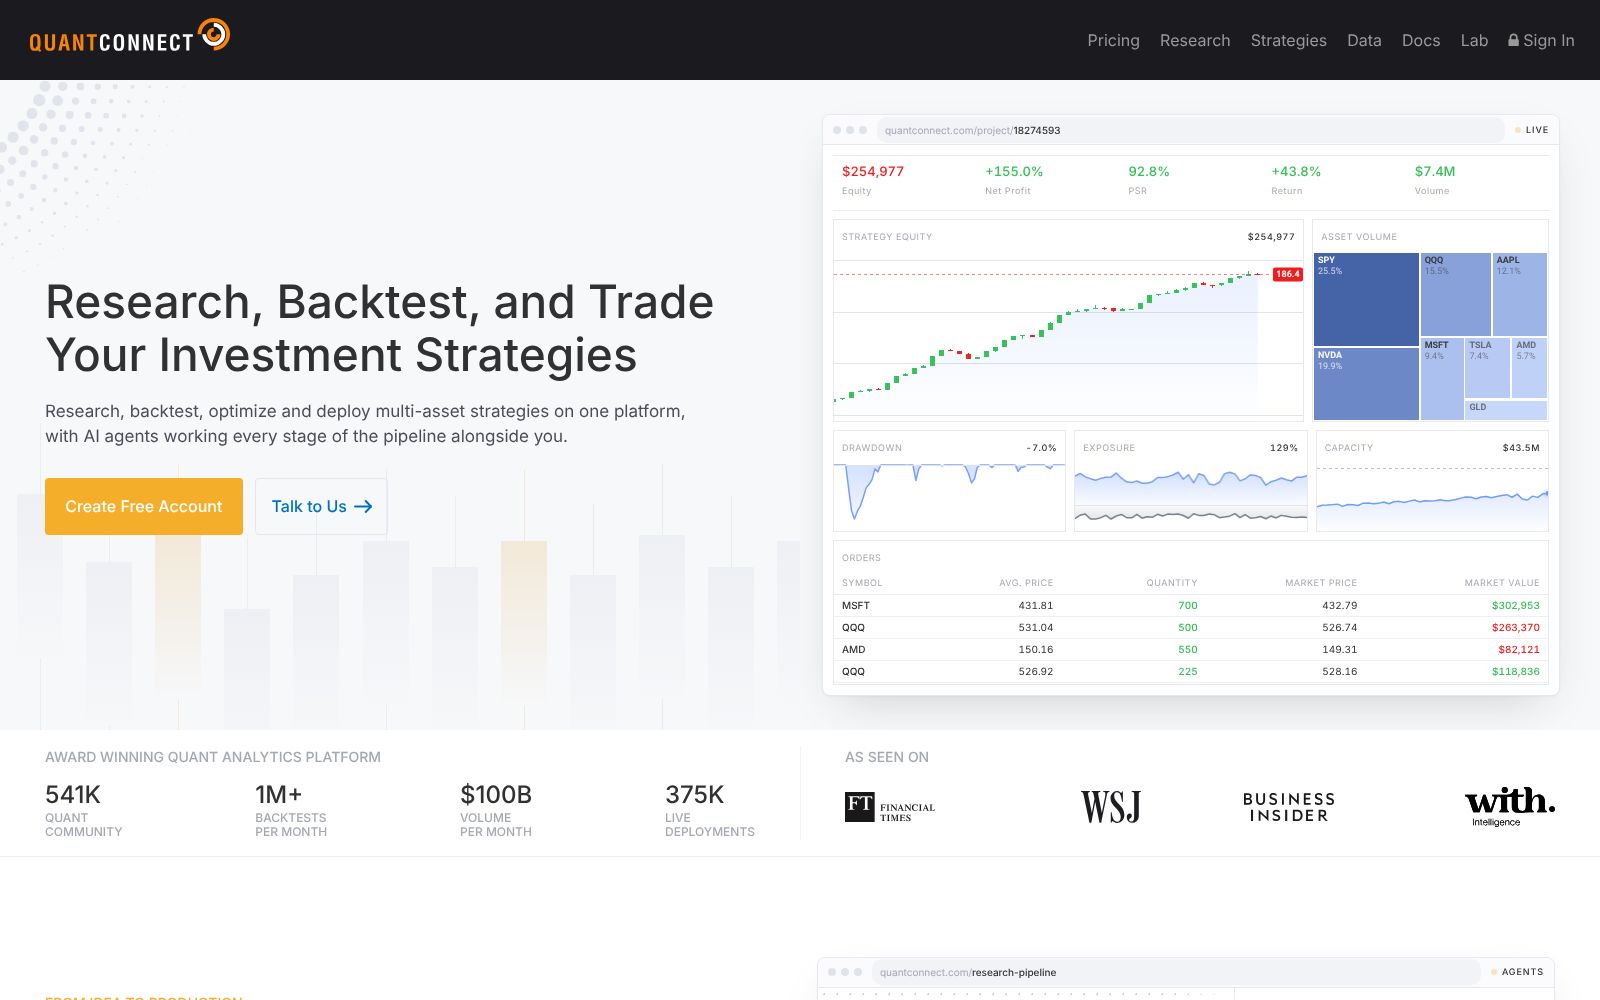
LEAN is a serious engine and QuantConnect gives retail traders something close to institutional research infrastructure for a few hundred dollars a month. That is the case for it, and it is a strong one. The case against comes from r/algotrading, where the complaints are unusually specific rather than vague: earnings date data wrong roughly three quarters of the time, intraday errors on heavily traded tickers, indicators returning identical values across different timeframes, and backtests hanging on the deployment page while the subscription bills. Some of those reports are older and the platform has moved since. But data quality and reliability are the two things a backtest cannot survive being wrong about, and they are exactly what the complaints are about.
The advertised seat prices are not the bill. QuantConnect calls them recommended setups, and the compute nodes you attach are priced separately in a tab we could not render from any automated client — the numbers are not in the page source, and QuantConnect's own docs point back at the pricing page for them. The seat minimums compound it: Team and Trading Firm require two users, Institution requires five, so the real floors are $336, $960 and $6,360 a month. And the free tier has a live trading node limit of zero, meaning live trading is impossible on it at any level of effort.
Hover, tap, or focus a card to see who we'd point at this tool — and who should walk away.
The traders who get the most out of QuantConnect.
Where QuantConnect is the wrong spend.
A real complaint from the trading forums, and what this tool actually does about it.
“1.) Their earnings report date data was incorrect about 75% of the time and when it was inaccurate, it was off by multiple weeks. 2.) Blatant intraday data issues and incorrect values for some of the most traded stocks/ETF's in the market. 3.) Indicators registered into their data consolidators were being updated with a single data interval, causing different timeframes to return the same indicator values. 4.) Indicators like PSAR and Ichimoku were making improper calculations when the proper data was passed through.”
Source: r/algotrading
Validate the data before you validate the strategy. Pick five tickers you know well, pull their earnings dates and a day of intraday bars, and check them against a second source before you run a single backtest. It costs an afternoon and it tells you whether the numbers underneath your results can be trusted. A backtest built on bad data does not fail loudly — it produces a clean equity curve that means nothing, which is the most expensive outcome available.
Sentiment pulled from one independent source, kept separate so you can weigh each one yourself.
 r/algotradingReddit
“Furthermore, simple quality of life issues drove me insane such as: half the time I'd launch a backtest, the process would just hang on the 'deployment' page and count forever without actually running a backtest (this despite paying $40 / mo. for upgraded backtesting nodes). Stack traces point to errors in the wrong line of your code (it's always a line above the actual error).”Read the original on Reddit →
r/algotradingReddit“Also... DOCUMENTATION. Documentation... documentation... realllly lacking”Read the original on Reddit →
r/algotradingReddit“Quantconnect just keeps becoming more trash by the day, to the point that now the same exact algorithm that worked fine before doesn't place orders anymore…”Read the original on Reddit →
r/algotradingReddit“No decline yet on my end. But my needs are probably different from yours. I've been using Quantconnect about the same amount of time and had my fair share of headaches for sure, but I havent encountered the above, fortunately. It isn't perfect, but i don't know of any other platform that offers such easy onboarding to live systematic trading.”Read the original on Reddit →
r/algotradingReddit“Quantconnect is still one of the best and reliabile platform. Did you use local deployement or quantconnect servers?”Read the original on Reddit →
Every quote is real and traceable. How we source them →
$0
Unlimited backtesting, 200 projects, 1 backtest node, 1 research node and ZERO live trading nodes. Minute to daily resolution only. No local CLI, no API, no paper trading, no live brokerage connections.
$84 / user / month
Local coding via VS Code and CLI, tick and second resolution, unlimited projects, up to 2 compute nodes, paper trading and live brokerage connections. 1 user.
$168 / user / month, minimum 2 users — so $336 / month floor
Adds project collaboration, higher log and file limits, up to 10 compute nodes, and the futures live feed included. Up to 10 users.
$480 / user / month, minimum 2 users — so $960 / month floor
Adds team project ownership, permissions, unlimited compute nodes, LEAN version control, and Trading Technologies, prime and FIX brokerage access.
$1,272 / user / month, minimum 5 users — so $6,360 / month floor
Adds the on-premises platform, AES-256 code encryption, bring-your-own-key AI routing, custom packages and IP access control.
Not published where we could verify it
Backtesting, research and live trading nodes are billed on top of the seat, and datasets are sold individually. Both sit behind JavaScript tabs. Price them at checkout before you commit.
Prices change. Check the vendor’s page before you buy.
One email a week. What we tested, what scored, and what we'd skip. Written for traders, not for clicks.